We receive compensation from the products and services mentioned in
this story, but the opinions are the
author's own. Compensation may impact where offers appear. We have not included all available products or offers.
Learn more about
how we make money
and
our editorial policies.
Advertiser Disclosure
All About Cookies is an independent, advertising-supported website. Some of the offers that appear on this
site are from third-party advertisers from which All About Cookies receives compensation. This compensation
may impact how and where products appear on this site (including, for example, the order in which they
appear).
All About Cookies does not include all financial or credit offers that might be available to consumers nor
do
we include all companies or all available products. Information is accurate as of the publishing date and
has
not been provided or endorsed by the advertiser.
Close
Editorial Policy
The All About Cookies editorial team strives to provide accurate, in-depth information and reviews to help
you, our reader, make online privacy decisions with confidence. Here's what you can expect from us:
All About Cookies makes money when you click the links on our site to some of the products and offers that
we mention. These partnerships do not influence our opinions or recommendations. Read more about how we
make money.
Partners are not able to review or request changes to our content except for compliance reasons.
We aim to make sure everything on our site is up-to-date and accurate as of the publishing date, but we
cannot guarantee we haven't missed something. It's your responsibility to double-check all information
before making any decision. If you spot something that looks wrong, please let us know.
Close
If you believe your identity has been stolen, contact the companies where the fraud happened, place a fraud alert or freeze with the credit bureaus, report the theft to the FTC, and file a police report if a creditor or other organization requires one.. The steps below walk you through the full process, and if you’re not sure your identity was stolen yet, start with the seven warning signs further down.
How quickly you act matters. In All About Cookies’ survey of 1,000 U.S. adults, about half of identity theft victims spotted the theft within two weeks, but only about a third recovered in that time. Victims lost $3,313 on average, and 23% say they’re still dealing with the fallout months or even years later.
You’re not alone, either. The FTC received more than 1.1 million reports of identity theft in 2024, a 9.5% increase over the prior year.
4.8
AllAboutCookies writers and editors score products based on a number of objective features as well as our expert editorial assessment. Our partners do not influence how we rate products.
2026 Editors’ Choice
Best Overall Identity Theft Protection Service
Identity Protection
Aura Identity Theft
ID theft protection that monitors your SSN, bank accounts, credit cards, and brokerage and retirement accounts for suspicious activity
Every plan includes the full feature set, so no additional cost to unlock monitoring, insurance, or restoration
Bundles data removal with identity theft protection, antivirus, VPN, and a password manager in one subscription
If you discover your identity has been stolen, act quickly to minimize damage to your credit history, finances, and legal standing.Start by contacting the companies where the fraud happened, placing a fraud alert, and reporting the theft at IdentityTheft.gov. These steps could help limit further misuse while you begin recovery.
1. Contact relevant companies
If you discover suspicious activity that might indicate identity theft, contact the companies and organizations involved right away.
For example, if you receive a credit alert for an unknown new account, reach out to the fraud department of that credit card issuer to find out more. If it's not an account you opened, inform the company of the identity theft and contact the credit bureau as well.
Ask them to close or freeze any accounts the thief used, then change the logins, passwords, and PINs for those accounts. Turn on two-factor authentication wherever it’s offered.
2. Place a fraud alert
If you suspect identity theft, place a fraud alert on your credit reports to ask potential lenders to verify your identity before opening new credit.
Contact one credit bureau to place the alert, and it must notify the other two.
Review your credit reports and every bank and credit account for unfamiliar accounts, transactions, or changes so you can identify what was compromised. You're entitled to free weekly credit reports from each of the three major bureaus — take advantage of these to get a full picture of the damage.
4. Freeze your credit
Unlike a fraud alert, a credit freeze restricts access to your credit report, which helps prevent identity thieves from opening new accounts in your name. Lift the freeze temporarily before applying for new credit.
Contact all three credit reporting agencies to do this:
This stops additional accounts from being opened in your name while you assess the full scope of the damage.
5. File a report with the FTC
File an identity theft report with the Federal Trade Commission (FTC) at IdentityTheft.gov. The site provides a personalized recovery plan and step-by-step guidance. If someone may have filed a tax return using your identity, also file a separate report with the IRS.
7. Contact other relevant agencies, companies, and banks
Depending on what information was compromised, contact all relevant agencies and institutions. If your driver's license was stolen, contact the Department of Motor Vehicles (DMV). If your employer uses a company credit card or has access to sensitive personal information, let them know as well.
Make a list of every company or organization that may need to be notified, including banks and card issuers connected to affected accounts. Contact each one and record the date, representative, and outcome. This record may also help when you file a police report.
8. File a police report
Contact your local police department and file a police report about the identity theft. Keep a copy of the report, as credit bureaus, banks, and card issuers may request it while they review and resolve fraudulent activity.
7 signs someone stole your identity
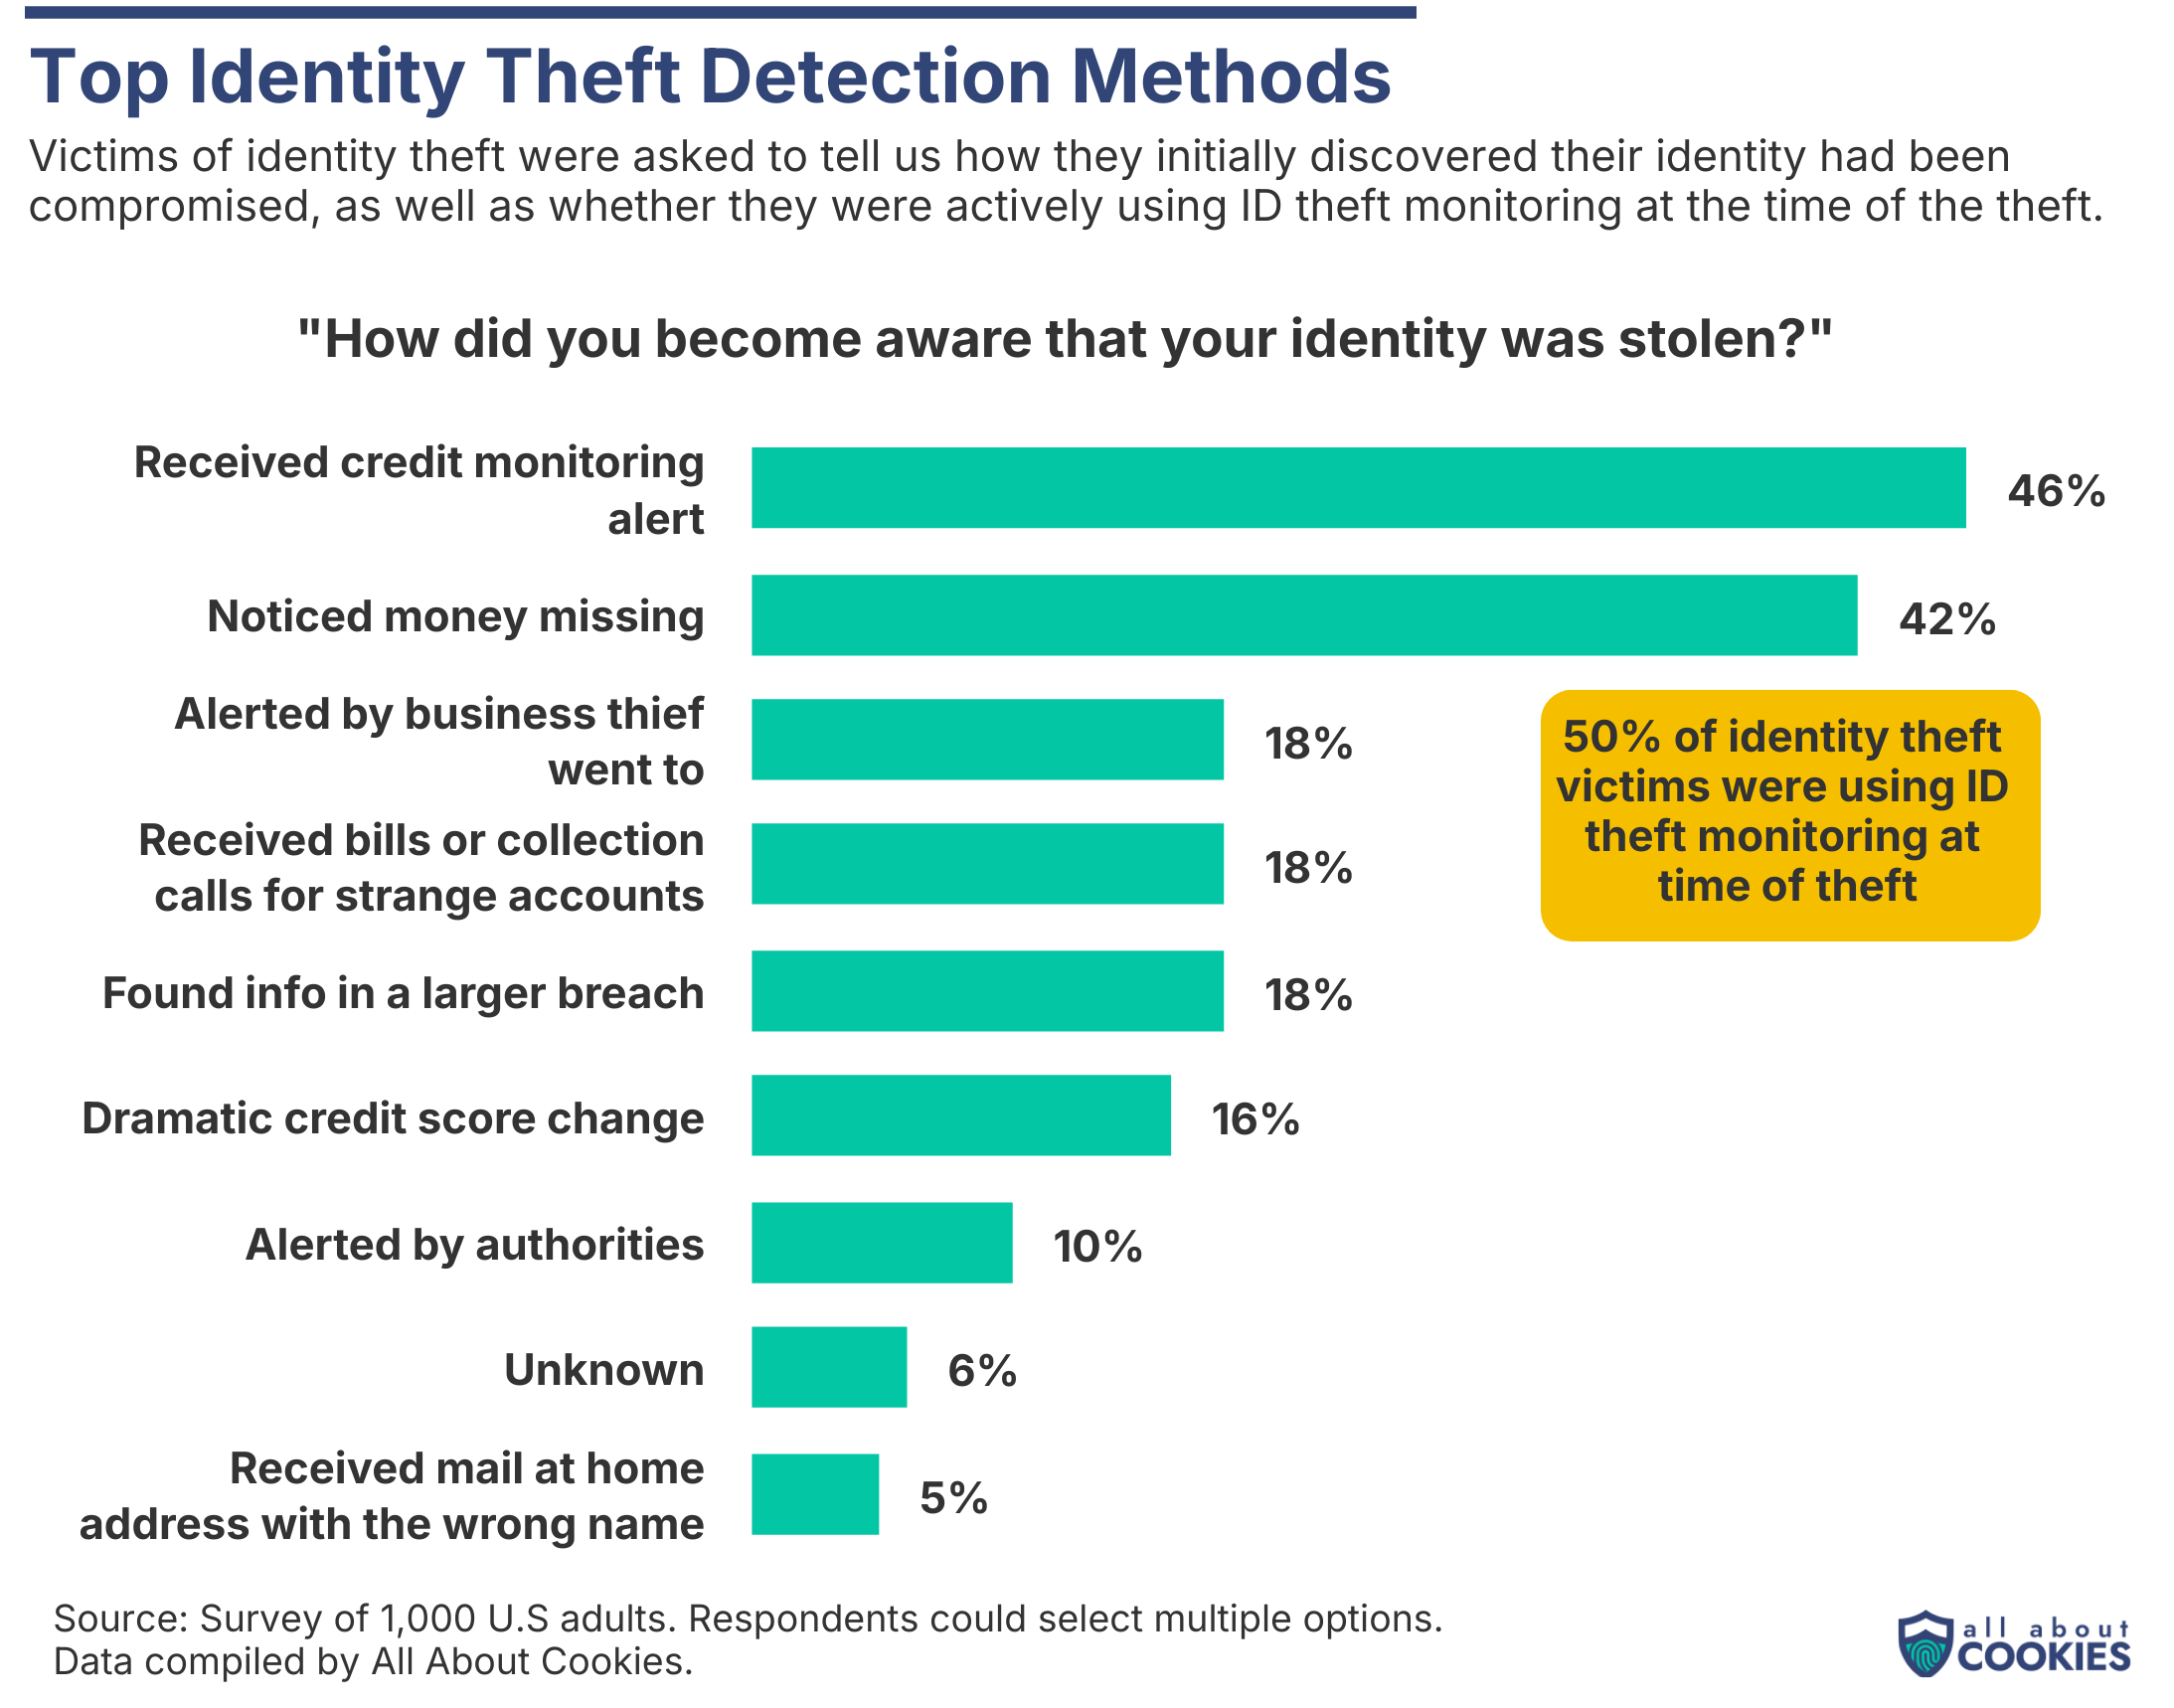
All About Cookies’ survey found that 42% of victims discovered the theft by noticing money missing from their accounts — making financial vigilance one of the most important detection tools available to you. Even more, 46%, found out through a credit monitoring alert.
Spotting identity theft early can limit the damage. Here are the most common warning signs. For a deeper look at each one and how to check for it, see our guide on how to tell if someone stole your identity.
You're getting unrecognized charges and bills: Unfamiliar transactions are one of the earliest signs of identity theft. Bills that suddenly stop arriving can also mean someone changed your address or contact details.
Your credit report has accounts you didn't open: Check your credit reports for accounts you don't recognize. You can get free reports from all three bureaus every week at AnnualCreditReport.com.
You receive collection calls for unknown debt: Calls about debts you don’t recognize may mean someone opened an account in your name. Ask the collector for a written debt validation letter, which must name the original creditor and the amount owed.
Your taxes are filed more than once: If the IRS says a return was already filed with your SSN, someone may have stolen your identity. To keep it from happening again, get an Identity Protection PIN from the IRS.
Unusual withdrawals from your bank account: Even small withdrawals or deposits you don’t recognize can mean someone has access to your financial information.
Accounts opened in your children's names: Children’s clean credit histories make them easy targets, and the theft can go unnoticed for years. If credit offers, bills, or collection notices arrive in your child’s name, see our guide on child identity theft.
Your information was part of a data breach: If your personal information was exposed in a data breach, your identity may be at risk. Act on breach notices right away rather than waiting to see if anything goes wrong.
4.8
AllAboutCookies writers and editors score products based on a number of objective features as well as our expert editorial assessment. Our partners do not influence how we rate products.
ID theft protection that monitors your SSN, bank accounts, credit cards, and brokerage and retirement accounts for suspicious activity
Every plan includes the full feature set, so no additional cost to unlock monitoring, insurance, or restoration
Bundles data removal with identity theft protection, antivirus, VPN, and a password manager in one subscription
How to prevent identity theft
Protecting your personal information and watching for suspicious account activity can reduce your risk of identity theft. Take these steps to protect your information:
1. Keep your credit reports frozen
Freezing your credit reports with all three bureaus makes it much harder for identity thieves to open new credit accounts in your name. A freeze does not stop unauthorized charges on existing accounts. Temporarily lift it before you apply for new credit, then refreeze it afterward.
2. Place fraud alerts when needed
If a credit freeze isn't practical, place a fraud alert to ask lenders to verify your identity before extending credit. An initial fraud alert lasts one year. Confirmed identity theft victims can request an extended alert that lasts seven years.
3. Check your mail often
Check your mail regularly for bills, statements, or account notices you do not recognize, and for expected mail that does not arrive. The United States Postal Service offers a free service called Informed Delivery that previews up to 10 pieces of incoming mail daily, helping you spot unexpected correspondence.
4. Review your banking and credit card statements
Review your bank and credit card statements at least monthly for charges or transactions you do not recognize. Report any unauthorized activity to the bank or card issuer immediately. Many banks and card issuers also offer free credit monitoring tools that may alert you to suspicious activity sooner.
5. Destroy documents containing sensitive information
Shred any documents containing your SSN, driver's license number, account numbers, or home address before discarding them. Thieves can combine personal details from multiple discarded documents to open accounts or impersonate you.
6. Use strong, unique passwords
If you suspect identity theft, change the passwords for affected accounts right away, starting with your email, financial, and shopping accounts. Our password behavior survey found that 82% of internet users practice unsafe password habits, including reusing passwords across multiple accounts. Reused passwords put other accounts at risk when one account is breached.
Learn how to create a strong password and consider using a password manager to generate and store unique credentials for every account.
7. Use an identity theft protection service
For ongoing monitoring, you can purchase an identity theft protection service. These services may monitor information such as your Social Security number, credit file, bank accounts, and the dark web, then alert you to suspicious activity. Some also provide identity restoration specialists and insurance coverage to help with recovery after identity theft.
You can also sign up for a free My Social Security account to review your earnings record and benefits information. Check whether your bank or card issuer includes free credit monitoring with your account.
Identity theft is a serious and growing crime. Our analysis of FTC data found that identity theft reports rose 9.5% in 2024 — the first year-over-year increase since 2021 — with credit card theft accounting for 40% of all reports. All About Cookies’ survey found that victims lose an average of $3,313, and nearly a quarter are still dealing with the aftermath today.
Knowing how to prevent identity theft helps lower your risk. If you suspect identity theft, freeze your credit, review your statements for unauthorized activity, change compromised passwords, and consider an identity theft protection service for ongoing monitoring.
FAQs
What is the first thing you should do if your identity is stolen?
First, contact the bank, credit card issuer, or other company connected to the suspected fraud and ask it to secure the affected account. Then report the identity theft to the Federal Trade Commission (FTC) and contact the credit bureaus to freeze your credit report.
Also consider filing a police report if it is needed for the recovery process.
What should you do if someone steals your Social Security number?
Immediately contact the three credit bureaus to freeze your credit report if someone steals your Social Security number.
You should also get a copy of your credit report to see if there are any fraudulent accounts. If so, contact the financial institution or company behind each account to report the theft. Finally, report the theft to the FTC at IdentityTheft.gov, which may help you build a recovery plan.
How common is identity theft?
In 2024, the FTC received more than 1.1 million identity theft reports. According to All About Cookies’ survey of 1,000 U.S. adults, 46% of people know someone who has had their identity stolen.
4.8
AllAboutCookies writers and editors score products based on a number of objective features as well as our expert editorial assessment. Our partners do not influence how we rate products.
Andrew Adams spent more than 12 years in legal marketing and communications before shifting to tech writing, and this experience shapes how he covers the regulatory layer of online privacy that most writers treat as fine print. He specializes in GDPR, CCPA, and identity theft protection, and has authored more than 80 articles for All About Cookies. He holds an M.B.A. from Westminster University.
Kate Quinlan is a Senior Editor at All About Cookies, where she has tested dozens of digital security tools and contributed to 500+ articles on data security, web building & hosting, VPNs, ad blockers, parental controls, and more. Before joining AAC, she managed a team of more than 150 writers at SuperSummary, where she developed editorial standards at scale. She holds a B.A. in Professional Writing from Kutztown University.